17.9%
vs 16.6% deposit growth
Bank credit against deposit growth, year on year, fortnight to 15 Oct 2026.
EETS Invest · A partnership proposal for banks
Daily savings, recurring and fixed deposits from your bank, offered inside the billing app restaurants already run on. Your product, your KYC, your balance sheet. We bring the owner, at the right moment, every day.
01 Why now
17.9%
Bank credit against deposit growth, year on year, fortnight to 15 Oct 2026.
802 mn
September 2026. Restaurants are among NPCI's top UPI merchant categories.
96%
are ₹2,000 or less: small, frequent and predictable, exactly what daily saving needs.
The deposits banks need already flow through restaurant counters every day, in small UPI tickets.
02 The segment
03 The product
I
₹500a day, fixed
Pigmy reimagined: a set amount every day by auto-debit. For cafés, tiffin centres and small eateries.
II
2%of each day's sales
Moves with the business: more on busy days, less on slow ones. Worked out by EETS after day close.
III
₹2 lakhfor a goal
Monthly instalments or a lump sum for festival stock, renovation or a second outlet.
Figures are examples. Products, rates, tenures and premature-withdrawal terms are set by the partner bank; EETS shows them and never sets them.
04 In the app
01
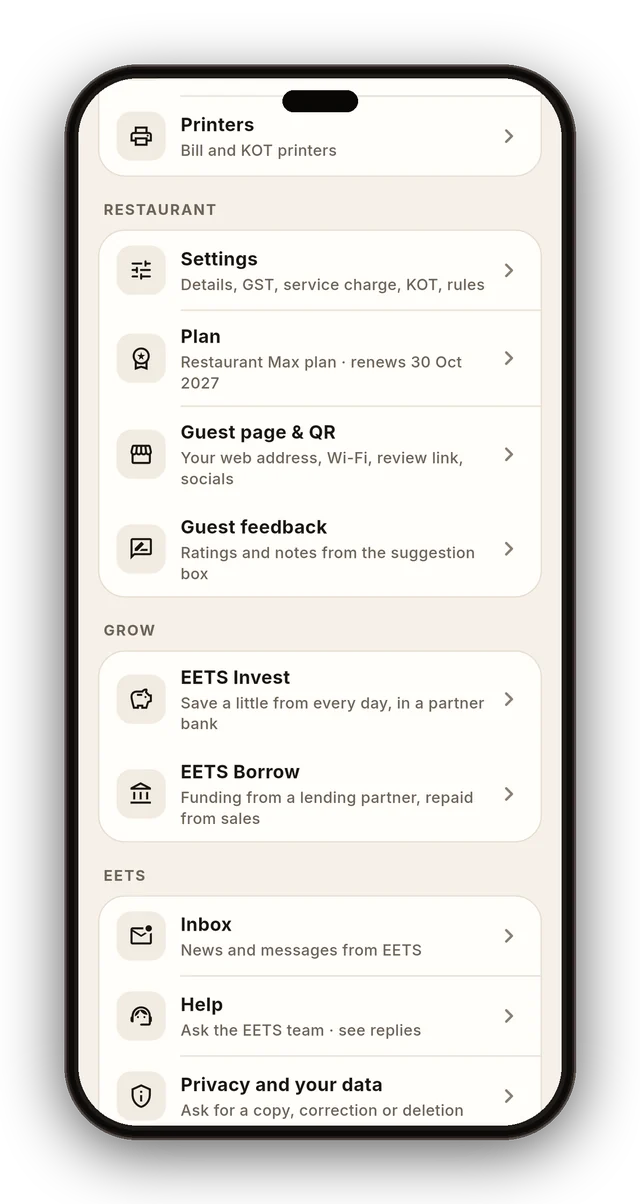
EETS Partner runs counter billing, captain ordering, the kitchen display and QR ordering all day. EETS Invest sits under More › Grow, visible only to the owner or manager.
02
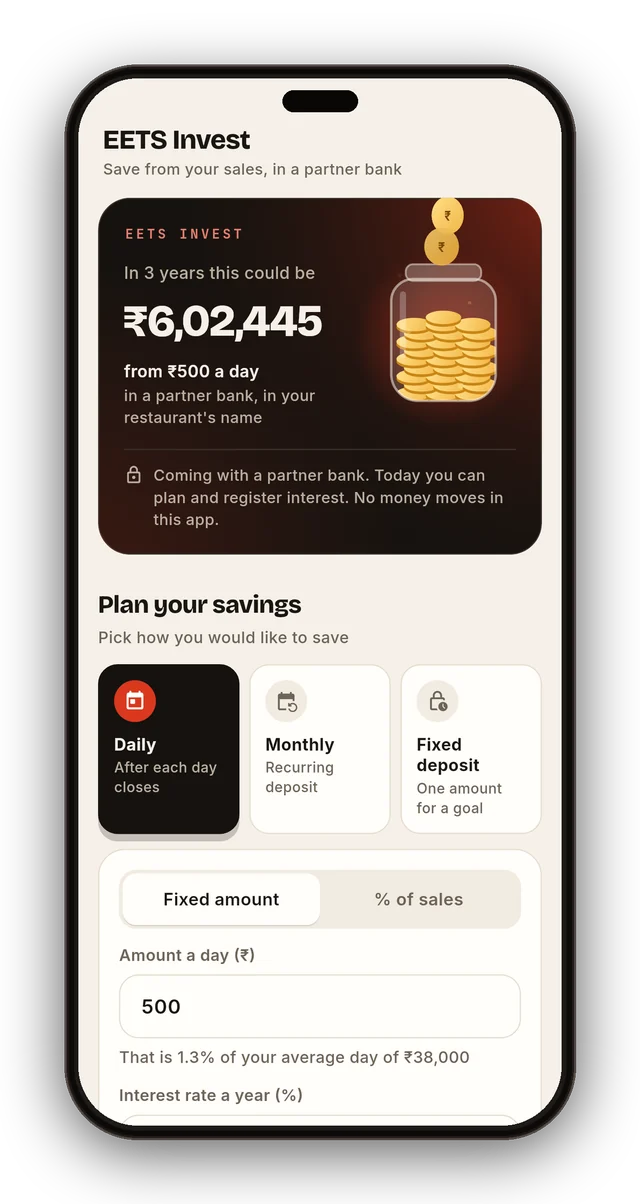
An animated jar of coins fills as the owner plans: ₹500 a day could be ₹6,02,445 in three years. Then pick daily, monthly or a fixed deposit.
03
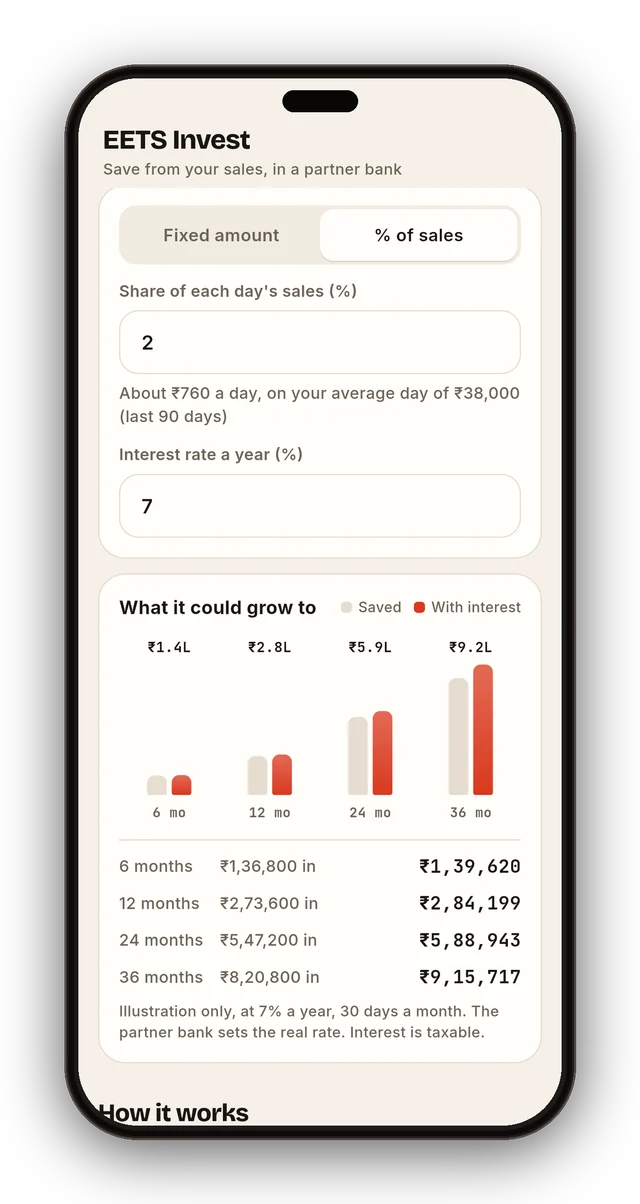
2% of sales on the sample restaurant's ₹38,000 average day is about ₹760 a day: ₹9.16 lakh in 36 months at an illustrative 7%. Every projection is labelled as an illustration.
04
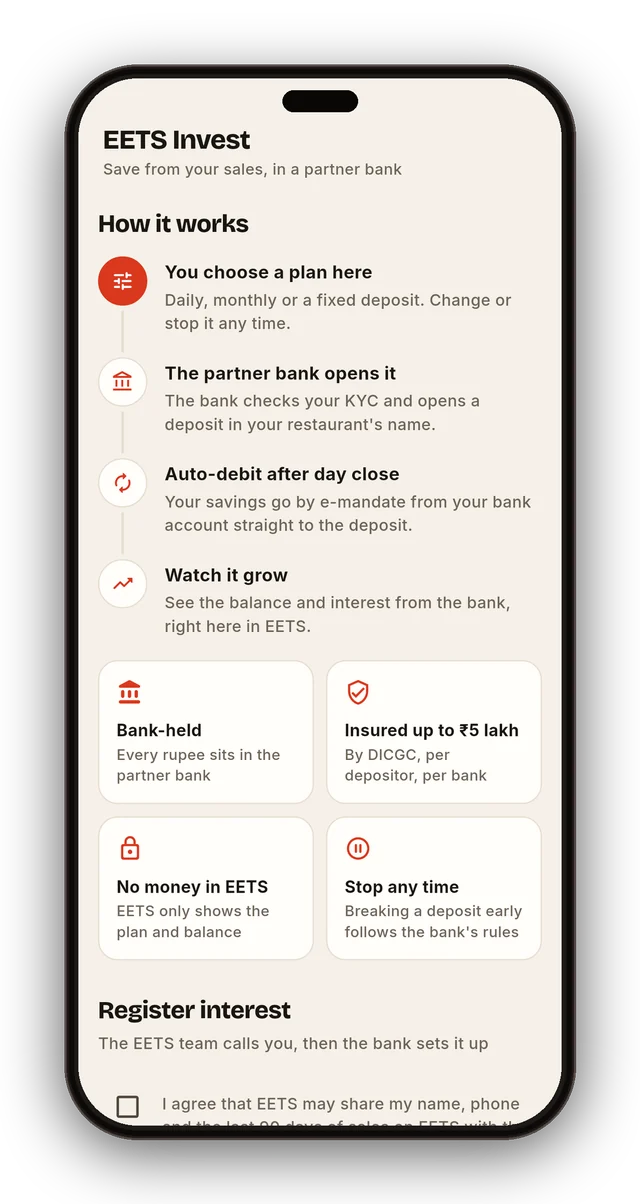
How it works, step by step, and four promises on every screen: bank-held, insured up to ₹5 lakh by DICGC, no money in EETS, stop any time.
05
Nothing is shared until the owner ticks consent. Your team updates the status; the owner sees each step in the app and gets an inbox message at every change.
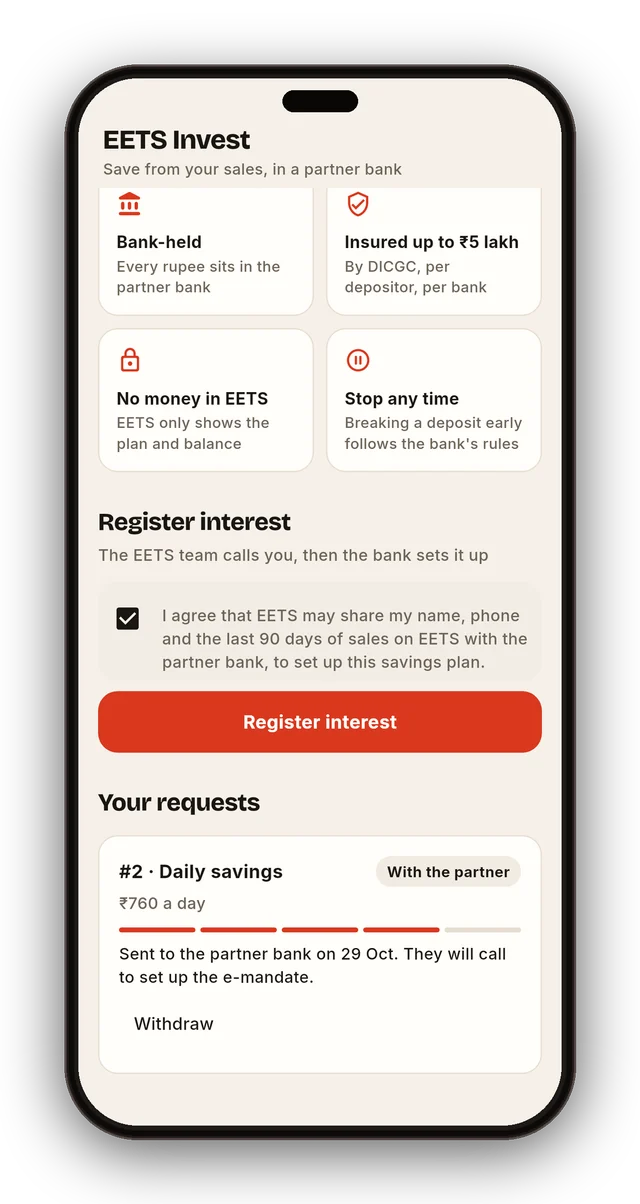
Real screens from the EETS Partner app, with sample restaurant data.
05 How money moves
06 Safeguards
EETS never receives funds with a promise to return them, which keeps it outside the Banning of Unregulated Deposit Schemes Act, 2019.
RBI's business correspondent framework already covers collecting small-value deposits. KYC and AML stay with your bank, under your BC and outsourcing policy.
Under RBI's 21 Apr 2026 e-mandate framework, debits up to ₹15,000 need no extra authentication, with a pre-debit notice and free cancellation.
Data reaches your bank only after the owner agrees, with a record of what was shared and when, under the DPDP Act 2023 and Rules 2025.
EETS data is stored in India, in Supabase's Mumbai region.
Every instruction sent and every status received is logged and open to your auditors and to RBI. Every screen states DICGC cover of ₹5 lakh per depositor per bank.
07 What your bank gets
Daily, small-ticket inflows from an owner segment few banks reach, spread across thousands of accounts.
No collection agent, no cash handling, no end-of-day reconciliation of collections.
90 days of verified takings at sign-up, shared with consent, to tailor the product and limits.
Deposit history today becomes underwriting for working capital tomorrow, against a ₹30 lakh crore MSME credit gap.
08 What a habit builds
Monthly compounding on 30 days of saving a month. Today's market: SBI 1-year RD 6.80%, Post Office RD 6.7% (Jul–Sep 2026). Your bank's rate applies.
One restaurant, 36 months (illustration)
₹6.02 lakh
Across the programme, 36 months (illustration)
₹30.1 crore
09 Who does what
| Area | Partner bank | Provantic (EETS) |
|---|---|---|
| Product, rates, terms | Designs and owns them | Shows them exactly as given |
| KYC and account opening | Does it, via its own journey or BC channel | Hands over consented interest |
| Holding the money | Every rupee, in the depositor's name | Never touches funds |
| Auto-debit | Runs UPI AutoPay or e-mandate | Suggests the daily amount from sales |
| Statements | Shares balances by API or Account Aggregator | Shows them in the app, with reminders |
| Customer service | Owns deposit complaints | First-line help in the app; routes to the bank |
| Marketing | Approves all wording | Promotes inside EETS and at onboarding |
10 Commercials and pilot
₹0
Nothing from Provantic, ever, for saving.
Per account
One-time, paid by the bank for each active deposit account opened through EETS.
Per year
A small share of average balances while the account stays active through EETS.
Shared
Each side builds its own end; we adapt to your existing APIs.
Proposed and open: final figures after the pilot shows activation and retention.
Weeks 1–4
Agree product and wording. Connect sourcing, mandate and statement APIs. Test consent and mandate end to end.
Weeks 5–8
Offer EETS Invest to restaurants already on EETS in Bengaluru, starting with THE NAAATI, our pilot restaurant.
Weeks 9–12
Accounts opened, mandates active, average daily saving and drop-off. Agree commercials and rollout.
Success measures, agreed before launch
Invited restaurants that open an account · Still saving after 60 days · Complaints per 100 accounts
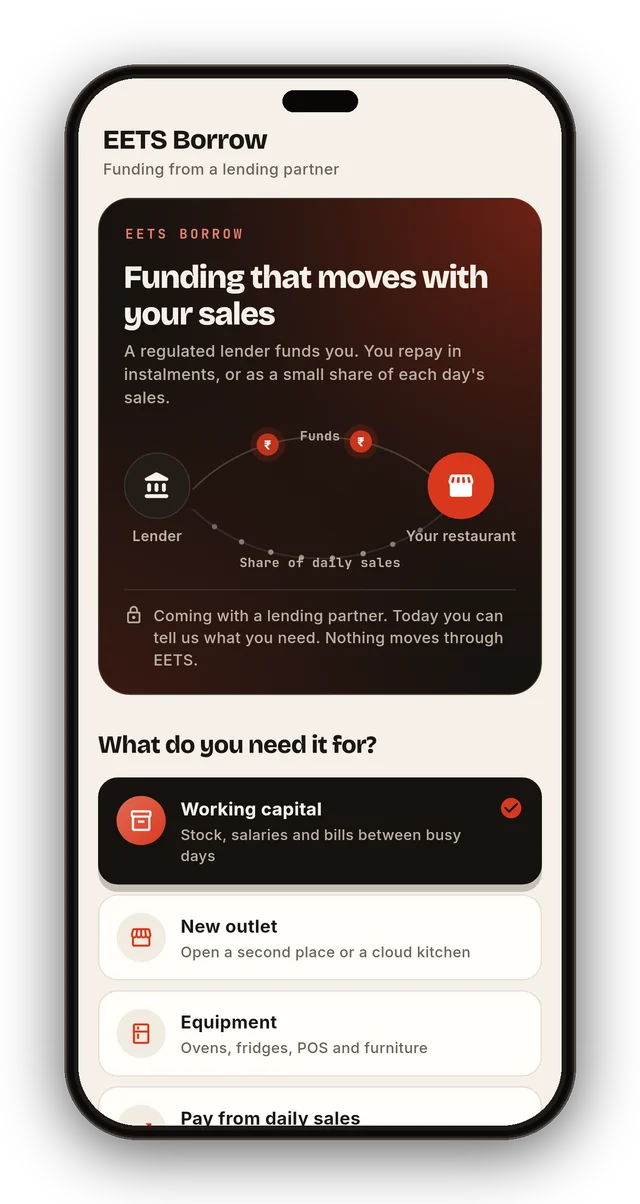
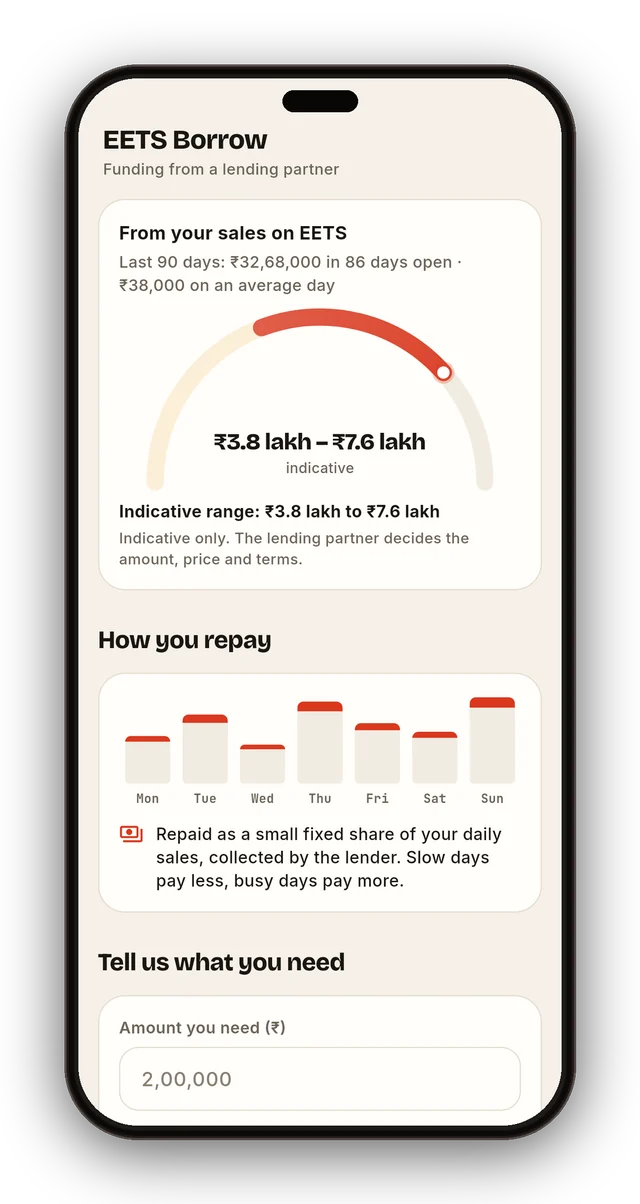
Next EETS Borrow
The same app already shows owners what a regulated lender could offer, from their own EETS sales: working capital, a new outlet, equipment, or funding repaid as a small share of each day's sales. EETS is the lending service provider; the lender decides, disburses and collects.
11 Next step
Pick a time that suits your team for a 30-minute call. We'll confirm by phone or email within one working day and send a calendar invite.
Premkumar RCEO, Provantic Technologies